What if an Israeli divorce agreement sets out how a U.S. 401(k) should be divided, but the plan still needs separate steps before it can act? For anyone considering dividing a US 401k in an Israeli divorce in Haifa, the key is to clarify both the divorce decision and the plan’s requirements before committing to a course of action.
It’s understandable to expect one agreement to resolve the issue. In practice, decisions made in Israel and the U.S. plan’s administration may raise separate questions. The account type, plan documents, administrator’s procedures, timing, and possible tax consequences can all affect the next steps. Check the details for the specific account rather than relying on assumptions.
This guide explains which account and plan records to gather, what to clarify about the relevant Israeli divorce process, and how to distinguish division terms from implementation requirements. It also outlines questions to raise with qualified legal and tax professionals in both countries. Israel Cross Border Law Firm offers family law and divorce law services in Israel. This article is general information, not legal advice or a substitute for advice about your circumstances. Legal services require a separate engagement.
Key Takeaways
- For dividing a US 401k in an Israeli divorce in Haifa, separate the divorce-related decision from the plan’s process for implementing it.
- Gather account statements and current plan materials, identify the plan administrator, and ask which requirements apply to this specific account.
- Compare proposed divorce terms with plan requirements, and confirm which legal and tax questions need review by qualified professionals.
- Before making or signing a proposal, clarify the relevant Israeli procedure and verify plan documentation, timing, and implementation steps.
- This article is general information, not legal advice. Get clarity before you commit. Request a confidential consultation.
U.S. 401(k) in Haifa Divorce: What to Clarify First?
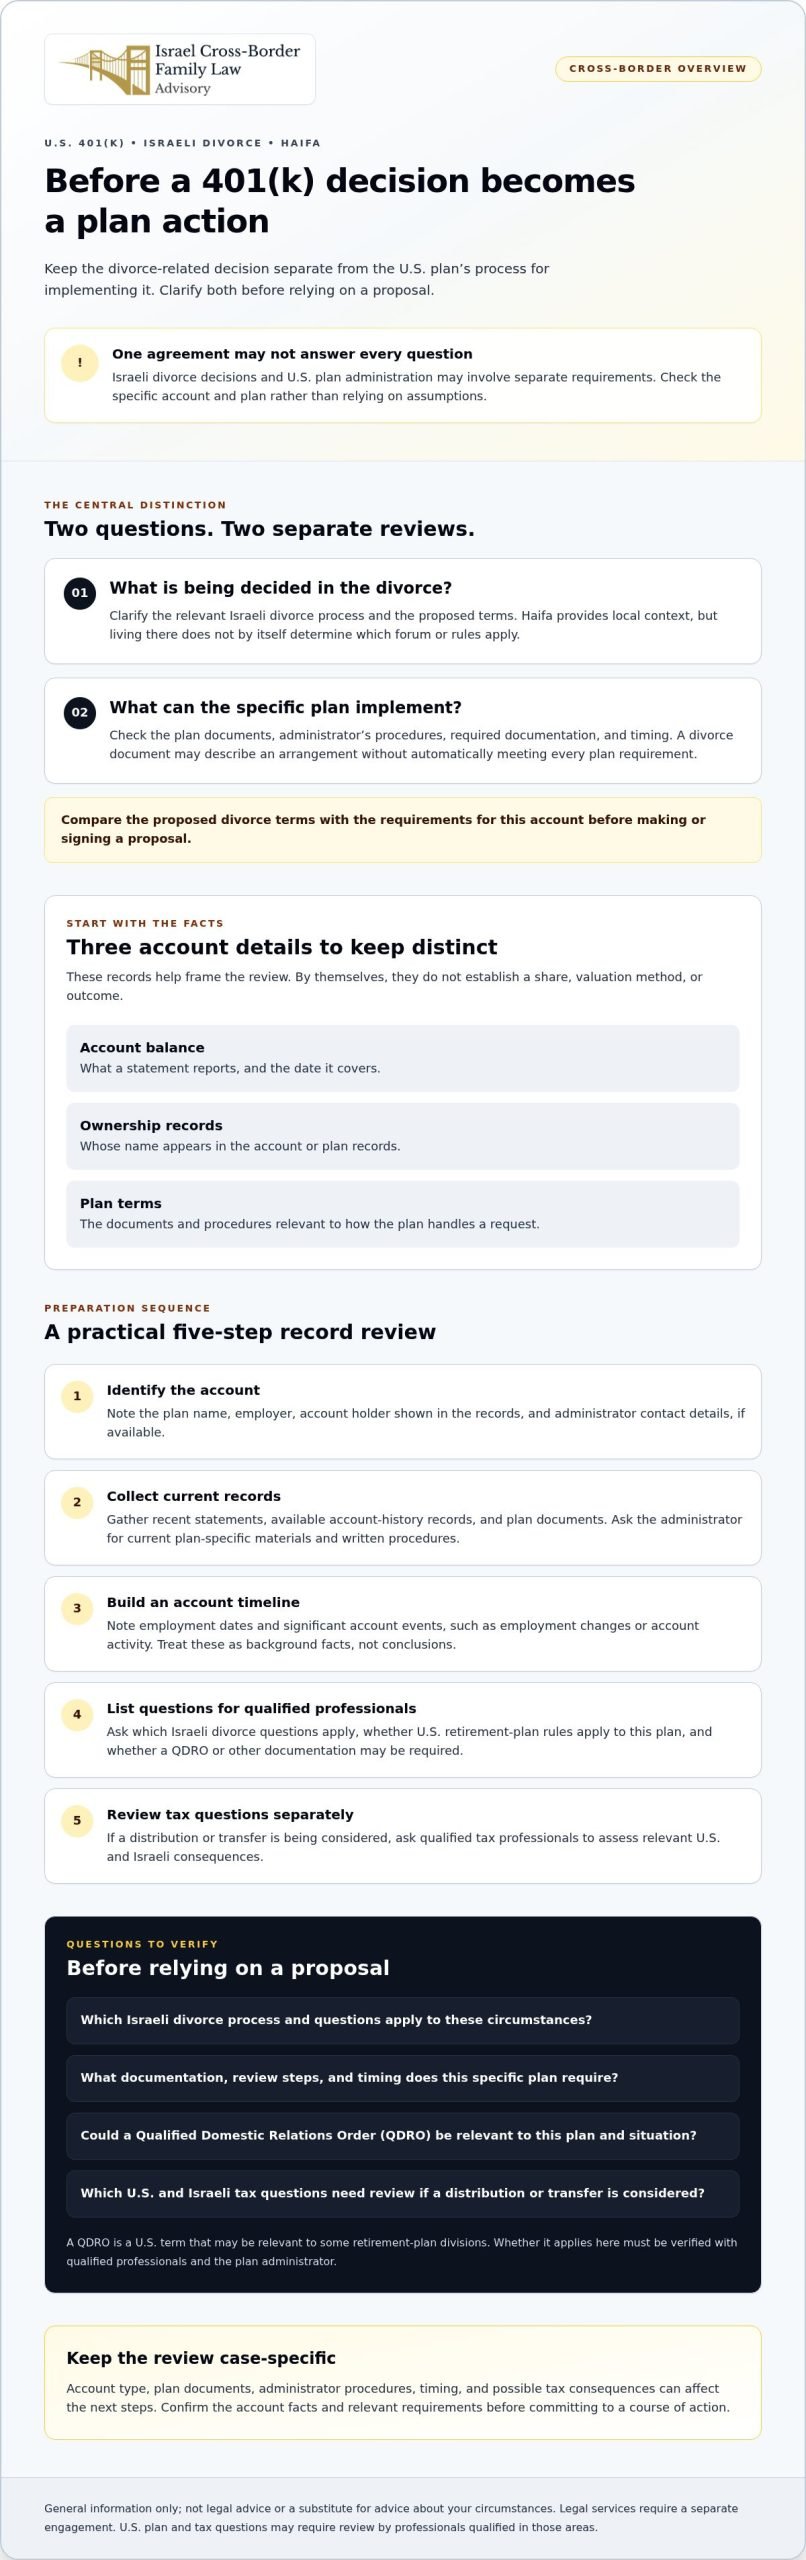
Dividing a U.S. 401(k) in an Israeli divorce requires case-specific review. The divorce-related decision and the plan’s ability to implement it are separate questions. Before relying on a proposal, clarify the relevant Israeli process, the account facts, and the requirements of the specific U.S. plan.
A 401(k) is a U.S. employer-sponsored retirement account. The plan documents and administrator’s procedures can affect how the account may be handled, so its general description alone doesn’t establish which steps are available. Haifa provides local context, but living there does not by itself determine which Israeli forum or rules apply.
What does “dividing a 401(k)” mean in a cross-border divorce?
Identifying an account is a fact-finding step. Deciding how it may be addressed in a divorce is a separate question, as is determining whether the plan can implement the proposed terms. Keep these details distinct:
- Account balance: What a statement reports and the date it covers.
- Ownership records: Whose name appears in the account or plan records.
- Plan terms: The documents and procedures relevant to the plan’s handling of a request.
These details don’t, by themselves, establish a share, valuation method, or outcome. A Qualified Domestic Relations Order (QDRO) is a U.S. term that may be relevant to some retirement plan divisions. Whether it applies to a particular plan and situation must be verified with qualified professionals and the plan administrator.
Why do Haifa and U.S. plan administration both matter?
Israeli divorce questions and a U.S. plan’s implementation process may need separate review. A divorce document may describe an arrangement, while the administrator may have its own documentation and review requirements. Don’t assume one document automatically satisfies every institution involved.
Confirm the relevant Israeli procedure and ask the plan administrator for current, plan-specific materials before relying on assumptions. For broader context, see cross-border guidance for expats and foreign nationals. The firm’s family and divorce law services may be relevant to questions about the Israeli side of a cross-border family matter. U.S. plan and tax questions may also require review by professionals qualified in those areas.
This article is general information, not legal advice or representation. Legal services require a separate engagement. Get clarity before you commit. Request a confidential consultation.
How to Map the 401(k) Plan, Account History, and Required Decision-Makers
A well-organized record set can help the relevant professionals identify what needs review, but documents alone cannot determine how an account should be treated or divided. Gather the facts first, then seek conclusions based on the specific plan and divorce circumstances.
Use this preparation sequence before a consultation:
- Step 1: Identify the account. Record the plan name, employer, account holder shown in the records, and contact details for the plan administrator, if available.
- Step 2: Collect relevant records. Gather recent statements, available account-history records, and plan documents. Ask the administrator for current plan-specific materials and written information about its procedures.
- Step 3: Build a timeline. Note employment dates and significant account events, such as changes in employment or account activity. Treat these as background facts, not conclusions about ownership or what may be addressed in the divorce.
- Step 4: List questions for review. Ask qualified professionals to assess which Israeli divorce questions apply, whether U.S. retirement plan rules apply to this plan, and whether a Qualified Domestic Relations Order (QDRO) or other documentation may be required.
- Step 5: Identify tax questions separately. If a distribution or transfer is being considered, ask qualified tax professionals to assess relevant U.S. and Israeli consequences. The IRS provides general information on IRS tax rules for foreign residents, but it cannot determine the outcome for an individual or account.
Which documents should you gather?
Start with records that show the account’s current details and available history. Include plan materials describing the administrator’s processes, if you have them. A simple timeline can help explain when the account existed and when notable events occurred. Don’t assume a date or statement establishes what portion may be relevant. That requires case-specific review.
Share records securely. Statements and plan documents may contain sensitive financial details, account identifiers, and personal information. Use a secure method when sending them, and avoid including unnecessary account credentials or access codes.
Which professionals and institutions may need to be involved?
The plan administrator can explain plan procedures and identify the materials it uses. It is not a substitute for legal or tax review. Depending on the circumstances, Israeli and U.S. professionals may need to coordinate, with each addressing questions within their own role. Confirm the specific participants and sequence for the case.
To understand the process before deciding on next steps, see how the advisory process works. You can also request a confidential advisory conversation to help organize the questions to verify. This article is general information, not legal advice or representation. Get clarity before you commit. Request a confidential consultation.
Israeli Divorce Decisions and U.S. 401(k) Rules: Questions to Compare
Dividing a US 401k in an Israeli divorce in Haifa does not necessarily mean the account can be divided automatically. The divorce-related decision and the U.S. plan’s ability to implement it are separate questions, and both require review based on the specific circumstances.
A divorce agreement or order may describe what the parties have decided. The plan administrator may separately need to assess whether its rules and required documents allow it to act. Don’t assume an Israeli document will be accepted by the plan, or that a plan procedure determines what the Israeli divorce decision should say. Recognition, enforceability, and whether a Qualified Domestic Relations Order (QDRO) applies are matters to verify for the individual case and plan.
Questions to compare
| Question | What needs to be checked | Who may be positioned to check it |
|---|---|---|
| What decision is being made about the account? | How the account is addressed in the divorce, and which Israeli forum or procedure is relevant. | An appropriately qualified Israeli family-law professional. |
| Can the plan carry out the proposed terms? | Current plan documents, administrator procedures, required forms, and whether a QDRO or other documentation is applicable. | The plan administrator can explain its process; a U.S. professional can review the legal questions. |
| Could implementation affect the financial result? | Possible tax treatment, timing, and consequences of any proposed transfer or distribution. | Qualified U.S. and Israeli tax professionals, as relevant. |
Does an Israeli divorce order automatically divide a U.S. 401(k)?
There is no safe assumption that it does. Whether a document can be recognized or enforced, and whether the plan can act on it, depends on applicable law, the plan’s terms, and professional review. Ask the relevant Israeli and U.S. professionals to check these points for the specific circumstances, and request the administrator’s current requirements before relying on a proposed arrangement.
What tax and timing questions should be checked?
Before agreeing to financial terms, clarify what steps may be needed, how long plan review could take, and whether a proposed transfer or distribution could have U.S. or Israeli tax consequences. The answers may depend on individual and account details. Don’t treat general information as a prediction of the net amount or completion date.
A Practical Haifa Checklist Before You Make or Sign a 401(k) Proposal
Before accepting proposed terms for a U.S. retirement account, use this checklist to identify what is known, what still needs confirmation, and who can address each open question. It is a preparation tool, not a way to reach legal conclusions on your own.
What should you clarify before accepting a proposed division?
- Check the records behind the proposal. Identify which statements and account-history documents it relies on, the date used for any account figure, and whether current plan documents were reviewed.
- Ask how the proposal would be carried out. Confirm what paperwork may be needed, which institution or plan administrator will review it, and whether the administrator has provided current, plan-specific instructions.
- Verify the relevant Israeli process. Ask a qualified Israeli family-law professional which forum and procedure apply to your circumstances. Haifa is the local context, but it does not by itself establish the applicable process.
- Separate the legal and administrative questions. Ask qualified professionals to check whether the proposed divorce terms and the plan’s implementation requirements align. Don’t assume a document will automatically be accepted by the plan.
- Check timing and tax implications. Before treating a proposed figure as final, ask qualified U.S. and Israeli tax professionals about possible consequences and ask the plan administrator about its review and processing steps.
A proposal may use an account value from a particular date, but that number is only one part of the picture. The plan’s records, the terms being discussed, and the way any proposed action could be implemented all need to be understood. Confirm these details before relying on the figure or signing terms based on it.
How can you prepare for a focused cross-border discussion?
Create a short timeline that separates documented facts from questions still awaiting an answer. Include relevant employment and account events, key divorce milestones, and any communications with the plan administrator. Mark missing records clearly rather than filling gaps with assumptions.
- Bring available statements, account-history records, and plan documents.
- List missing materials and any unanswered questions from the administrator.
- Note which issues need review in Israel, in the U.S., or by tax professionals.
- Keep sensitive account information secure when sharing documents.
This preparation can help professionals coordinate while keeping their roles clear: the administrator explains plan procedures, and qualified legal and tax professionals review questions within their areas of expertise. For more information about a possible confidential case review, consult the relevant service information before deciding whether that step suits your needs.
Choosing Your Next Step for a U.S. 401(k) in a Haifa Divorce
A practical next step is to move from gathering facts to resolving specific questions: first understand the account and plan, then identify which legal issues need review, and finally confirm what the plan requires to implement any proposed arrangement. The right sequence depends on the account, plan documents, and divorce circumstances.
For dividing a US 401k in an Israeli divorce in Haifa, avoid treating a draft agreement, account statement, or general explanation of U.S. rules as a complete answer. Each may inform the discussion, but none alone confirms how the account can be addressed or what steps the administrator will accept.
When may an advisory conversation help clarify your options?
A focused conversation can help you organize the available records, distinguish established facts from unanswered questions, and prepare a list for the relevant professionals. For example, you might identify missing plan documents, the Israeli process that needs review, and what to ask the administrator about implementation requirements.
This kind of discussion can provide context, but it isn’t legal advice and does not replace advice from qualified professionals. It also cannot control a court’s or plan administrator’s decision. Direct tax questions to qualified tax professionals familiar with the relevant circumstances.
What should you understand before committing to legal services?
Before entering a separate legal engagement, make sure you understand its scope, who will be responsible for each part of the work, and what decisions or documents may be needed next. In a cross-border matter, clarify which issues concern the Israeli divorce process and which concern U.S. plan administration. Don’t assume one professional or institution can answer questions outside its role.
Taking time to clarify the process before committing can help you make an informed choice about what to do next.
Take a Clear, Informed Next Step
Dividing a US 401k in an Israeli divorce in Haifa calls for more than agreeing on an account figure. The plan’s records and terms, the relevant Israeli divorce questions, and the U.S. administrator’s implementation requirements each need appropriate review.
Start by gathering account and plan documents, then identify the questions that remain open. Confirm the relevant Israeli process and ask whether specific U.S. plan requirements, including any QDRO requirement, apply. Before treating proposed terms or figures as final, clarify possible tax and timing implications with qualified professionals.
Israel Cross Border Law Firm offers family law and divorce law services in Israel. A consultation can help you understand whether to discuss your Israeli family law questions with the firm. Any legal services require a separate engagement, and U.S. plan or tax questions may require other qualified professionals.
Taking time to clarify those details can help you make decisions with greater confidence, one question at a time.
Frequently Asked Questions
Can a U.S. 401(k) be divided in an Israeli divorce?
A U.S. 401(k) may be addressed in an Israeli divorce, but the outcome depends on the specific account, applicable legal rules, and plan terms. For dividing a US 401k in an Israeli divorce in Haifa, distinguish the divorce decision from the plan’s ability to implement it. Gather account and plan records, then have qualified professionals review the proposed approach before relying on a particular division or result.
What is a QDRO, and is one needed for a 401(k) in an Israeli divorce?
A Qualified Domestic Relations Order, or QDRO, is a U.S. term for an order that may be relevant to dividing certain retirement plans in divorce. Whether a QDRO applies to a particular 401(k) depends on the plan and circumstances. Ask the plan administrator and a qualified U.S. professional to confirm the requirements. Don’t assume an Israeli divorce document is equivalent or that a QDRO is always required.
What documents should I gather before discussing a 401(k) in a Haifa divorce?
Gather available account statements, plan documents, account-history records, and communications from the plan administrator. Note relevant employment and divorce dates, and mark missing records or unanswered questions. These facts help professionals understand the account history, but don’t by themselves establish ownership or entitlement. Share documents securely and avoid sending account passwords or access codes. A qualified professional can identify what additional records may be relevant.
Can I agree on a 401(k) division before checking the plan requirements?
You can discuss possible terms, but it’s prudent to understand plan procedures and potential implementation issues before treating a proposal as final. Ask the administrator which documents it requires and how it reviews them. Qualified legal and tax professionals can assess other questions within their roles. The sequence and consequences depend on the plan and circumstances, so avoid relying on general assumptions or informal estimates when making financial decisions.
Could dividing a U.S. 401(k) in an Israeli divorce have tax consequences?
It could raise tax questions, but the treatment depends on the account, proposed arrangement, timing, and applicable rules. General information can’t determine the tax result for either spouse or estimate the amount received after a transaction. Before agreeing or acting, ask qualified U.S. and Israeli tax professionals to review the specific circumstances and explain potential consequences. Clarifying those issues early can help inform decisions about proposed terms.
Who should I speak with about dividing a 401(k) in a Haifa divorce?
Start by identifying the plan administrator and gathering available account records. Then ask qualified professionals to review the U.S. plan questions, relevant Israeli divorce issues, and tax questions within their roles. Israel Cross Border Law Firm offers family law and divorce law services in Israel, and may be a resource for questions about the Israeli family law process. This guidance may be relevant whether you live in Haifa, Tel Aviv, Jerusalem, Herzliya, Ra’anana, Netanya, Modi’in, Beit Shemesh, Kfar Saba, Hod Hasharon, Ramat Gan, Givatayim, Petah Tikva, Ashdod, Be’er Sheva, Eilat, Caesarea, or Zichron Ya’akov.

Article by
Gabriel Lior
A Personal Journey That Became a Mission
The advisory was founded by an American father Gabriel Lior, LLB, MBA , global entrepreneur, and cross-border advisor who spent more than a decade navigating the Israeli family court system firsthand and now lives in Singapore with his son.
As a divorced parent in a cross-border family, Gabriel faced nearly every legal challenge a foreign parent can encounter in Israel — including child custody disputes, child support proceedings, property matters in Israel and abroad, false accusations, and complex immigration and relocation proceedings.
Over the years, he learned the hard way how difficult it is for non-Israeli parents to understand the system, identify the right legal strategy, and choose the right legal representation — especially when language, culture, and jurisdictional differences are involved. He also witnessed how foreign parents and new immigrants are often disadvantaged or taken advantage of by service providers and institutions simply because they lack local knowledge or fluency.
From Client to Advisor
To truly understand — and survive — the system, Gabriel pursued formal legal education in Israel, completing two Israeli law degrees, alongside a BA and MBA earned in the United States. This was never about becoming a practicing attorney, but about gaining a deep, structural understanding of how the system works — and where it breaks down for foreign parents.
This rare combination of:
Firsthand client experience
Israeli legal and US business education
International business and negotiation training
Decades of commercial execution
created a unique perspective – one that understands both sides of the table.
After years of litigation, persistence, and at times self-representation, he ultimately succeeded in securing custody of his son and relocating abroad through a rare legal victory in the Israeli Supreme Court — becoming one of the first fathers in Israel to do so under these circumstances.
Disclaimer
Important Disclaimer:
The information provided on this website and in its content is for general informational and educational purposes only and does not constitute legal advice, legal opinion, or legal representation.
Gabriel Lior is not licensed to practice law in Israel (nor is he interested in doing so) and does not provide legal services, despite having completed 2 Law Degrees. The services offered are advisory in nature and are intended to provide general guidance, strategic insight, and information regarding cross-border family law considerations.
No attorney-client relationship is formed by accessing this website, reading its content, or communicating with us.
Any decisions made based on this information are at your own discretion and risk. For legal advice specific to your situation, you should consult a licensed attorney in the relevant jurisdiction.
Where appropriate, we may refer clients to independent, licensed attorneys or professionals. Such referrals do not constitute legal representation and no liability is assumed for services provided by third parties.