Navigating the complexities of a cross-border inheritance can be a daunting experience, particularly when confronted with the potential for significant, unforeseen tax liabilities in a foreign jurisdiction. For international beneficiaries with assets in Israel, the primary concern is understanding the financial implications of the inheritance tax Israel for foreigners. While Israel abolished its direct estate tax in 1981, providing a measure of relief, this does not eliminate all financial and legal obligations. The process for securing and liquidating assets remains a sophisticated challenge that requires precise legal and fiscal navigation.
This comprehensive 2025 guide is engineered to provide definitive clarity and a strategic roadmap. We will move beyond the simple non-existence of a direct inheritance tax to explore the crucial ancillary taxes, such as Capital Gains Tax, that may apply. You will gain a clear understanding of the Israeli probate or succession order process, the potential for tax liabilities in your home country, and the necessary steps to protect your assets confidently from abroad. Our objective is to empower you with the expert knowledge required to manage your Israeli inheritance efficiently and without costly complications.
Key Takeaways
- While Israel does not impose a direct inheritance or estate tax, foreign beneficiaries must navigate a different set of critical financial and legal obligations to secure their assets.
- Inherited Israeli real estate is a primary area of concern, as its subsequent sale can trigger significant Capital Gains Tax (CGT) liabilities that require careful management.
- Securing an Israeli Probate Order or Inheritance Order is a mandatory legal prerequisite for transferring assets, a multi-jurisdictional process with specific procedural requirements for non-residents.
- Understanding the interplay between the lack of inheritance tax in Israel for foreigners and your home country’s tax laws is critical to developing a strategy that mitigates the risk of double taxation.
- Proactive estate planning can substantially reduce future tax burdens and streamline the complex inheritance process for your international heirs, ensuring a more efficient transfer of wealth.
The Core Answer: Does Israel Levy an Inheritance or Estate Tax?
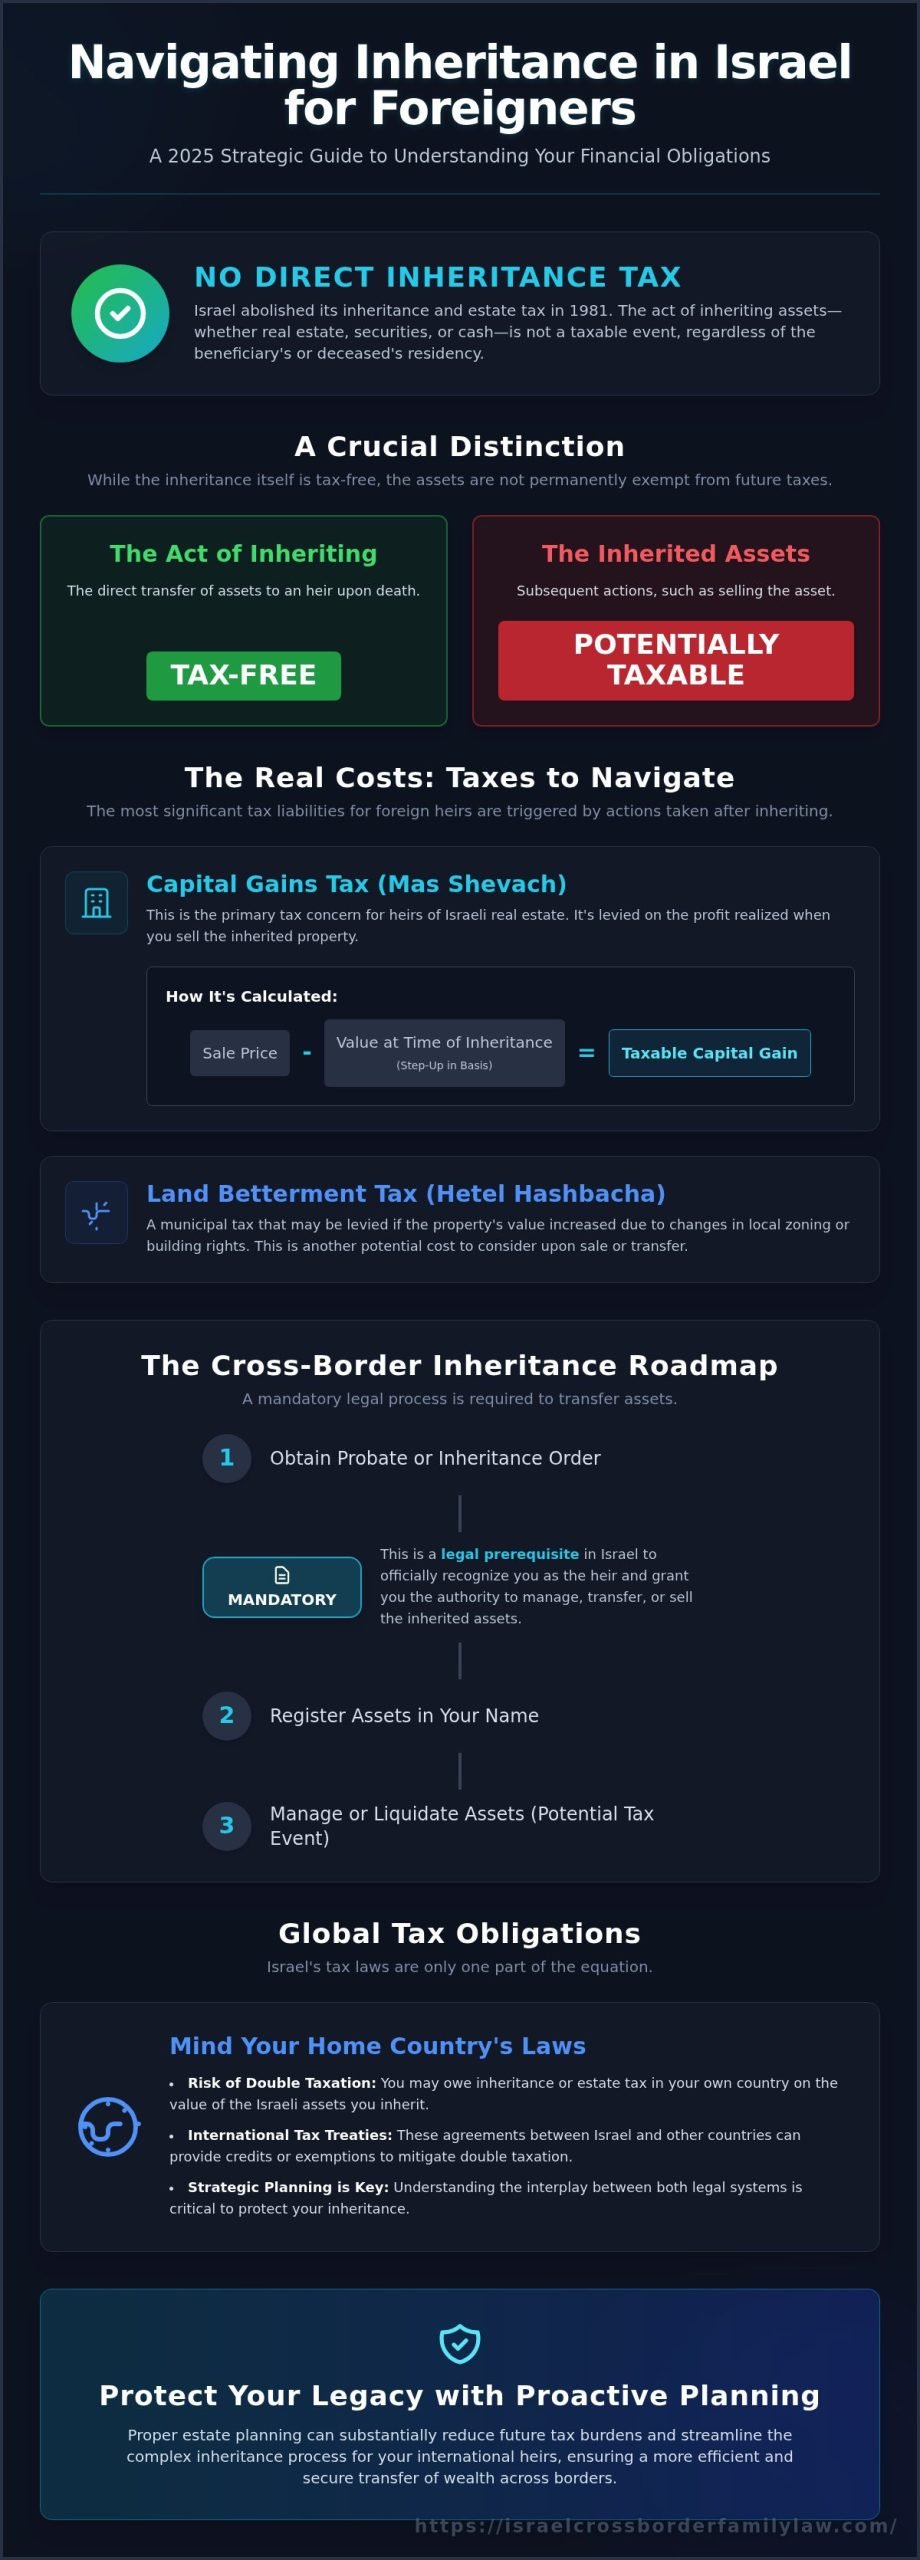
For non-residents and Israeli citizens navigating cross-border estate matters, the primary question is often the most direct. The answer is unequivocal: Israel does not impose an inheritance tax or an estate tax. This applies universally, regardless of the beneficiary’s or the deceased’s citizenship or residency status. The transfer of assets upon death, whether real estate, securities, or cash, is not considered a taxable event in and of itself.
This policy provides a clear framework, but it is essential to understand the full scope of potential financial implications. To better understand the multi-jurisdictional complexities, particularly involving U.S. assets, the following overview is highly relevant.
Understanding the Abolition of Israel’s Estate Tax
In a significant legislative move, Israel abolished its inheritance tax in 1981. This decision positions Israel in stark contrast to many Western nations, such as the United States and the United Kingdom, where substantial estate and gift taxes form a core component of fiscal policy. This legal landscape makes Israel an attractive jurisdiction for holding certain types of assets, as their direct transfer to heirs upon death does not trigger a tax liability at the state level.
The Key Distinction: Tax on Inheritance vs. Tax on Assets
It is imperative for foreign heirs to comprehend a crucial distinction: while the act of inheriting is not taxed, the underlying assets are not permanently exempt from future taxation. This is the most significant concept within the conversation about inheritance tax israel for foreigners. For instance, if a non-resident inherits a real estate property in Jerusalem, no tax is due at the moment of transfer. However, should the heir decide to sell that property later, the transaction will be subject to Israel’s Capital Gains Tax (Mas Shevach) on the appreciation in value.
The Real Costs: Taxes Foreigners Must Navigate When Inheriting Israeli Assets
While Israel does not impose a direct estate or inheritance tax, non-resident beneficiaries must be aware of other significant tax liabilities. The misconception that inheriting Israeli assets is entirely tax-free can lead to costly surprises. The critical distinction is that these taxes are not levied upon the act of inheritance itself but are triggered by subsequent actions, most commonly the sale or transfer of the inherited asset. Understanding this transactional nature is fundamental for anyone evaluating the topic of inheritance tax israel for foreigners. The transfer of property is governed by a sophisticated framework of Israeli inheritance laws, and navigating the subsequent tax implications requires precise legal and financial planning.
Capital Gains Tax (Mas Shevach) on Inherited Property
The most significant tax for heirs of Israeli real estate is the Capital Gains Tax, known locally as Mas Shevach. This tax is applied to the “real” profit-or capital gain-realized upon the sale of the property. For inherited assets, the gain is calculated as the difference between the sale price and the property’s market value on the date of the original owner’s passing. This “step-up in basis” can substantially reduce the taxable amount. While exemptions exist, particularly for a sole residential apartment, the qualifying criteria are stringent and often do not apply to non-resident owners. This tax is due at the time of the property sale.
Land Betterment Tax (Hetel Hashbacha)
A Land Betterment Tax, or Hetel Hashbacha, is a municipal levy imposed when a property’s value increases due to changes in local zoning or building plans (e.g., approval for an extension or additional floors). This is a liability attached directly to the property, which is passed on to the heir. The tax is calculated as 50% of the increase in the property’s value attributable to the municipal action. Typically, this liability is settled when the property is sold or when a new building permit is issued.
Tax Implications for Other Assets (Businesses, Securities)
The principles of transactional taxation extend to other types of assets. Inheriting shares in an Israeli company or other securities is not a taxable event. However, when the non-resident heir decides to sell these shares, the sale will be subject to Israel’s standard capital gains tax rules. Inheriting an active business presents a far more complex scenario, involving corporate law, ongoing tax obligations, and potential liabilities that require specialized cross-border legal and accounting guidance to properly manage.
The Cross-Border Inheritance Process: A Roadmap for Foreign Heirs
Navigating the Israeli legal system from abroad presents a unique set of challenges. For foreign heirs, securing an inheritance requires a structured, multi-step approach that intersects directly with Israeli property and tax law. While there is currently no direct inheritance tax in Israel for foreigners, the process of liquidating and repatriating assets involves significant tax considerations, particularly Capital Gains Tax on property sales. Successfully managing this complex process necessitates experienced legal counsel in Israel. This roadmap outlines the critical path for expats and foreign nationals to claim and manage their Israeli inheritance.
Step 1: Obtaining an Israeli Inheritance Order or Probate Order
The foundational step is to legally validate your claim as an heir. This is achieved by petitioning the Israeli Registrar of Inheritance for one of two orders. If the deceased left a valid will, your legal representative will file for a Probate Order (Tzav Kiyum Tzava’a). In the absence of a will (intestacy), a petition is filed for an Inheritance Order (Tzav Yerusha), which distributes the estate according to Israeli succession law. Foreign heirs must provide crucial documentation, including an original or authenticated death certificate (often requiring an apostille), the original will if applicable, and formal proof of kinship.
Step 2: Registering the Asset in the Heir’s Name
Once the Inheritance or Probate Order is granted, it serves as the legal instrument to transfer ownership of the decedent’s assets. For real estate, your Israeli attorney will use this order to register the property in your name at the Israel Land Registry Office (Tabu). Critically, this direct transfer from the decedent to a legal heir is generally exempt from both Land Appreciation Tax and Acquisition Tax. This registration is a mandatory prerequisite; you cannot legally market, sell, or transfer the property to a third party until the title is formally in your name.
Step 3: Managing Tax Filings and Payments from Abroad
Executing an asset sale and managing the subsequent financial obligations from overseas is logistically complex. By granting a power of attorney to your Israeli lawyer, they can act on your behalf to manage the entire transaction. This includes negotiating the sale, reporting the transaction to the Israel Tax Authority, and handling the assessment for Capital Gains Tax. To facilitate this, it is highly advisable to open an Israeli bank account to receive the proceeds of the sale and pay any requisite taxes. After all liabilities are settled, your legal counsel will manage the repatriation of the net funds to your bank account abroad, ensuring full compliance with Israeli law.
Navigating International Tax Treaties and Home Country Obligations
For foreign beneficiaries, a primary concern is the potential for double taxation-being taxed on the same asset in both Israel and their country of residence. While Israel does not levy an estate tax, this does not eliminate tax obligations in the heir’s home jurisdiction. The interaction between Israeli tax law and foreign tax law creates a complex, multi-jurisdictional challenge where specialized cross-border legal and tax guidance is not just beneficial, but essential for compliance and asset protection.
The Role of the US-Israel Tax Treaty
The Convention Between the Government of the United States of America and the Government of the State of Israel for the Avoidance of Double Taxation is a critical framework for US heirs. Its primary purpose is to prevent the same income from being taxed by both countries. For example, if you inherit and subsequently sell an Israeli property, the capital gains tax paid to the Israel Tax Authority can often be claimed as a foreign tax credit against your US tax liability on that same gain, mitigating the risk of double payment.
US Taxpayer Obligations for Foreign Inheritances
It is crucial for American citizens and residents to understand that they are taxed on their worldwide income. Receiving a substantial inheritance from abroad triggers specific and stringent reporting requirements, even if the issue of inheritance tax israel for foreigners is not applicable at the Israeli level. Key obligations include:
- IRS Form 3520: US beneficiaries must file this form to report inheritances or gifts from a foreign person valued at more than $100,000.
- Significant Penalties: Failure to file Form 3520 on time can result in substantial penalties, calculated as a percentage of the inheritance value, even if no tax was ultimately due.
Strategic Planning for Non-US Foreign Heirs
Heirs residing in other countries, such as the United Kingdom, Canada, or EU member states, face similar cross-border complexities. Each country maintains its own tax treaty with Israel, with unique provisions and credit mechanisms. These beneficiaries must consult with a tax advisor who has deep expertise in the specific bilateral treaty governing their situation. While the core Israeli principle of no inheritance tax remains, the reporting duties and potential tax liabilities in your home country demand careful, professional navigation.
Successfully managing a cross-border inheritance requires a sophisticated understanding of international tax law. To ensure compliance and optimize your financial outcome, engaging with experienced counsel is the most prudent course of action.
Proactive Planning: How to Minimize Future Tax Burdens for Your Heirs
Navigating the complexities of a cross-border inheritance after a loved one has passed is a challenging, reactive process. A far more effective approach is proactive estate planning. While the direct framework for inheritance tax israel for foreigners is currently non-existent, this does not eliminate the significant administrative, legal, and potential tax liabilities that can arise from other jurisdictions. For individuals with assets in both Israel and abroad, sophisticated planning is not a luxury-it is essential for protecting your legacy and simplifying the process for your beneficiaries.
Properly structured estate planning provides certainty and control, ensuring your assets are distributed according to your precise wishes without undue delay or cost. It is the most valuable step you can take to safeguard your family’s future.
Crafting a Multi-Jurisdictional Will
Relying on a single foreign will to govern Israeli assets can lead to protracted and costly probate proceedings in Israel. A strategically drafted Israeli will, designed to work in concert with your primary will, is a cornerstone of effective cross-border estate management. The key is careful coordination to ensure the wills complement, rather than revoke, one another. Key benefits include:
- Expedited Probate: An Israeli will is recognized by local courts, significantly accelerating the process of obtaining an inheritance order.
- Clarity and Precision: It specifically addresses Israeli assets, from real estate to bank accounts, leaving no room for ambiguity.
- Reduced Legal Complexity: It avoids the need for foreign legal documents to be translated, authenticated, and interpreted under Israeli law.
Using Trusts for Cross-Border Asset Protection
For more complex asset portfolios, establishing a trust offers a superior level of control and protection. A trust is a powerful legal instrument that can hold and manage assets on behalf of your beneficiaries, often bypassing the public probate process entirely. An Israeli trust can be structured to hold local property for foreign beneficiaries, providing a seamless mechanism for asset transfer and long-term management. This strategy can offer enhanced privacy, asset protection, and greater control over the timing and conditions of distributions to heirs.
The intricacies of multi-jurisdictional estate law demand expert guidance. Structuring your assets to minimize future tax burdens and administrative hurdles for your heirs is a complex undertaking. To ensure your estate is optimized for a smooth international transfer, we invite you to schedule a Confidential Case Review to discuss your unique circumstances with our experienced team.
Secure Your Legacy: Navigating the Complexities of Israeli Inheritance
Navigating the transfer of Israeli assets requires a nuanced understanding of its unique legal framework. While the absence of a direct inheritance tax israel for foreigners is a significant advantage, heirs must still contend with other critical financial obligations, such as Capital Gains Tax on property sales and their own home country’s tax liabilities. This multi-jurisdictional complexity underscores the vital importance of proactive estate planning to safeguard asset value and ensure a seamless transfer to the next generation.
Our firm provides authoritative guidance through these challenges, leveraging deep expertise in US-Israel cross-border law and a proven track record in complex international inheritance cases. We advise on both Israeli and US tax obligations to secure your financial interests. Schedule a confidential consultation to navigate your Israeli inheritance with clarity and confidence. Let us help you protect your family’s future and honor your legacy.
Frequently Asked Questions
Is there really no inheritance tax in Israel at all for foreigners?
It is correct that Israel does not levy an estate or inheritance tax, a policy established in 1981. This applies universally to residents and non-residents alike. Therefore, the discussion of inheritance tax israel for foreigners focuses not on Israeli obligations, but on the potential tax liabilities in the beneficiary’s home country. Beneficiaries must consult with tax advisors in their own jurisdiction to understand their reporting requirements and potential tax consequences upon receiving assets from an Israeli estate.
Do I have to pay capital gains tax if I inherit an Israeli property but don’t sell it?
No, the act of inheriting an Israeli property does not trigger a capital gains tax liability. This tax, known in Israel as Mas Shevach for real estate, is only applicable upon the eventual sale of the asset. The taxable gain is calculated based on the appreciation in value from the date the deceased originally acquired the property to the date of its sale by the heir. Holding the inherited property does not create a taxable event.
How long does the inheritance process take in Israel for someone living abroad?
The timeline for a cross-border inheritance process is contingent upon the case’s complexity. A straightforward probate or inheritance order, with a valid will and no disputes, can often be secured within 6 to 12 months. However, matters involving multi-jurisdictional legal challenges, asset location difficulties, or will contests can extend this process significantly, often to 18 months or longer. Proactive legal management is key to navigating this efficiently.
What happens if my foreign will is not valid under Israeli law?
Should a foreign will be declared invalid under Israeli law, the estate will be distributed according to Israel’s statutory rules of intestacy. This legal framework dictates a specific hierarchy for distribution, typically prioritizing the surviving spouse and children. To ensure a foreign will’s validity, it is imperative that it conforms to the legal formalities of either the jurisdiction where it was executed, the testator’s domicile, or Israeli law itself, necessitating expert cross-border legal review.
Do I need to travel to Israel to claim my inheritance?
It is generally not necessary for a non-resident beneficiary to travel to Israel to manage their inheritance. An experienced law firm can act on your behalf through a limited Power of Attorney, which must be notarized and apostilled in your country of residence. This legal instrument empowers your Israeli counsel to handle all court filings, engage with the Administrator General, and execute the transfer of assets, ensuring a seamless process without requiring your physical presence.
How much are the legal fees for handling an international inheritance case?
Legal fees for managing a complex, international inheritance case are determined by the estate’s value and the sophistication of the required legal work. While some matters may be handled on an hourly basis, a common structure is a percentage of the estate’s total value, often ranging from 1.5% to 3% plus VAT. For a standard case, fees could start from ₪20,000 to ₪50,000, though a precise quotation is provided following a thorough assessment of the specific file.

Article by
Gabriel Lior
A Personal Journey That Became a Mission
The advisory was founded by an American father Gabriel Lior, LLB, MBA , global entrepreneur, and cross-border advisor who spent more than a decade navigating the Israeli family court system firsthand and now lives in Singapore with his son.
As a divorced parent in a cross-border family, Gabriel faced nearly every legal challenge a foreign parent can encounter in Israel — including child custody disputes, child support proceedings, property matters in Israel and abroad, false accusations, and complex immigration and relocation proceedings.
Over the years, he learned the hard way how difficult it is for non-Israeli parents to understand the system, identify the right legal strategy, and choose the right legal representation — especially when language, culture, and jurisdictional differences are involved. He also witnessed how foreign parents and new immigrants are often disadvantaged or taken advantage of by service providers and institutions simply because they lack local knowledge or fluency.
From Client to Advisor
To truly understand — and survive — the system, Gabriel pursued formal legal education in Israel, completing two Israeli law degrees, alongside a BA and MBA earned in the United States. This was never about becoming a practicing attorney, but about gaining a deep, structural understanding of how the system works — and where it breaks down for foreign parents.
This rare combination of:
Firsthand client experience
Israeli legal and US business education
International business and negotiation training
Decades of commercial execution
created a unique perspective – one that understands both sides of the table.
After years of litigation, persistence, and at times self-representation, he ultimately succeeded in securing custody of his son and relocating abroad through a rare legal victory in the Israeli Supreme Court — becoming one of the first fathers in Israel to do so under these circumstances.
Disclaimer
Important Disclaimer:
The information provided on this website and in its content is for general informational and educational purposes only and does not constitute legal advice, legal opinion, or legal representation.
Gabriel Lior is not licensed to practice law in Israel (nor is he interested in doing so) and does not provide legal services, despite having completed 2 Law Degrees. The services offered are advisory in nature and are intended to provide general guidance, strategic insight, and information regarding cross-border family law considerations.
No attorney-client relationship is formed by accessing this website, reading its content, or communicating with us.
Any decisions made based on this information are at your own discretion and risk. For legal advice specific to your situation, you should consult a licensed attorney in the relevant jurisdiction.
Where appropriate, we may refer clients to independent, licensed attorneys or professionals. Such referrals do not constitute legal representation and no liability is assumed for services provided by third parties.